Great Power Competition, Strategic Forecasting
The SWIFT Alternative: De-Dollarization, Financial Statecraft, and the Fragmentation of the Global Monetary Order
De-dollarization is accelerating but the dollar still dominates SWIFT, reserves, and trade finance. A data-driven assessment of CIPS, mBridge, and BRICS Pay.
Executive Summary
The global monetary order is not collapsing, but it is fragmenting at the margins in ways that matter strategically. Since Russia’s central bank reserves were frozen in February 2022, a coalition of states — led by China, Russia, and elements of the Gulf and the wider Global South — has invested heavily in payment infrastructure, digital-currency platforms, and reserve diversification designed to reduce single-point dependence on the US dollar and the SWIFT messaging network. At the same time, the empirical record through mid-2026 shows the dollar retaining a commanding position across every major metric: it accounts for roughly half of global SWIFT payment value (and closer to 60 percent once intra-eurozone transactions are excluded), 57 percent of official foreign-exchange reserves, over 80 percent of trade-finance value, and one side of nearly nine in ten foreign-exchange transactions globally.
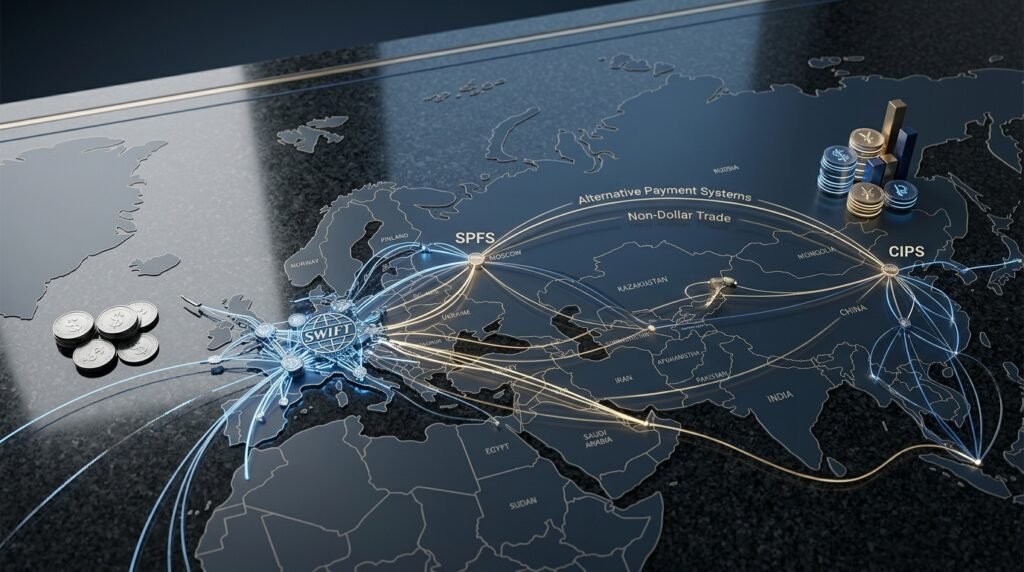
This assessment argues that the accurate description of the current moment is neither “de-dollarization is a myth” nor “the dollar’s collapse is underway,” but something more specific and more strategically consequential: the emergence of parallel, only partially interoperable financial infrastructures — China’s Cross-Border Interbank Payment System (CIPS) and the BIS-incubated mBridge platform on one side; SWIFT, the G7-aligned Project Agorá, and dollar-denominated stablecoins under the new GENIUS Act framework on the other. States are not choosing one system over the other so much as building redundancy into both, hedging against the risk that financial infrastructure — as the freezing of Russian reserves demonstrated — can be weaponized by the state that controls it.
This report examines the historical foundations of dollar primacy, the strategic context created by financial sanctions since 2014 and especially 2022, the technological and institutional architecture of the principal alternatives (CIPS, mBridge, BRICS Pay, digital ruble, e-CNY), the political fault lines within BRICS itself, the legal precedents being set by the treatment of Russia’s frozen assets, and the countervailing effect of dollar-pegged stablecoins. It closes with scenario analysis, probability-weighted forecasts through 2030, and a strategic outlook for policymakers, financial institutions, and multinational treasurers navigating an increasingly bifurcated system.
Key Judgments
- [High confidence] The US dollar remains dominant across reserves, payments, trade finance, and foreign-exchange turnover, and no single currency or payment system is positioned to displace it within the next five years.
- [High confidence] De-dollarization, where it is occurring, is a story of diversification and redundancy-building at the margins rather than a systemic rupture; aggregate dollar-share declines in official reserves are driven substantially by exchange-rate valuation effects rather than active portfolio reallocation by central banks.
- [High confidence] The February 2022 freezing of approximately $300 billion in Russian central bank reserves is the single most important proximate driver of the post-2022 surge in official-sector gold accumulation, functioning as a demonstration effect that dollar- and euro-denominated reserve assets are politically contingent rather than unconditionally sovereign.
- [Moderate confidence] Cross-border financial infrastructure is bifurcating into two largely non-overlapping technological ecosystems — a China-led bloc built around CIPS and mBridge, and a G7-aligned bloc built around SWIFT, Project Agorá, and regulated dollar stablecoins — with most Global South states maintaining access to both rather than choosing exclusively.
- [Moderate confidence] BRICS as an institution has explicitly deprioritized a common currency in favor of interoperable local-currency payment rails (BRICS Pay), reflecting an unresolved internal divide between states seeking sanctions-resilience (Russia, and to a lesser extent China) and states such as India that retain a strategic and economic stake in continued dollar-system stability.
- [Moderate-high confidence] US digital-asset policy, chiefly the GENIUS Act and the resulting growth of dollar-pegged stablecoins, is emerging as a countervailing force that extends dollar-denominated private financial infrastructure into precisely the retail and emerging-market channels that central bank digital currencies (CBDCs) were expected to capture.
- [Low-to-moderate confidence, forecast] Absent a systemic shock — a Taiwan contingency triggering China-scale secondary sanctions, a US fiscal or confidence crisis, or a decision by Washington to weaponize dollar clearing against a systemically important economy — the current bifurcated, multipolar-but-dollar-centered equilibrium is likely to persist through the remainder of the decade.
Introduction
Financial infrastructure has quietly become one of the principal arenas of great-power competition. Where twentieth-century strategic competition was fought primarily through military alliances, arms races, and proxy conflicts, twenty-first-century competition increasingly runs through the pipes of the international payments system: who can send money to whom, in what currency, cleared through which institution, and under whose legal jurisdiction. The Society for Worldwide Interbank Financial Telecommunication (SWIFT) — a Belgian cooperative that does not itself move money but transmits the standardized messages that instruct banks to do so — has become a proxy battleground for this contest precisely because its centrality to the dollar-based system makes it, and the currency it predominantly carries, an instrument of coercive statecraft.
This assessment addresses three interlocking questions that policymakers, financial institutions, and strategic planners must answer with precision rather than rhetoric: First, how much has the international monetary system actually diversified away from the dollar, as distinct from how much diversification has been announced or aspired to? Second, what alternative infrastructures — CIPS, mBridge, BRICS Pay, SPFS, e-CNY — have reached operational maturity, and what structural constraints limit their scale? Third, what are the second-order and long-term implications of a bifurcating financial order for sanctions policy, sovereign-debt markets, defense procurement, and the strategic autonomy of middle powers, including Pakistan and its immediate region?
Historical Background
The dollar’s centrality is not accidental; it was constructed deliberately across three distinct historical junctures, and each has left an institutional residue still visible today.
Bretton Woods (1944) established the dollar as the anchor of the postwar monetary order, pegged to gold at $35 per ounce, with other currencies pegged to the dollar. Forty-four Allied nations, meeting in New Hampshire, effectively transferred the reserve-currency role from sterling — exhausted by two world wars — to the dollar, backed by the fact that the United States held roughly half of global manufacturing output and the majority of the world’s monetary gold at the time.
The Nixon Shock (1971) severed the dollar’s convertibility into gold, ending Bretton Woods’ fixed-exchange-rate architecture and inaugurating the fiat-dollar era. Contrary to expectations that this would weaken the dollar’s standing, the system that emerged — sometimes termed Bretton Woods II — entrenched dollar centrality further, because the dollar’s value now rested not on a commodity peg but on the depth, liquidity, and legal reliability of US Treasury markets, and on the network effects of a currency already used to invoice the majority of world trade.
The Petrodollar Arrangement (1974) between the Nixon administration and Saudi Arabia — under which Riyadh priced its oil exports in dollars and recycled the proceeds into US financial assets in exchange for security guarantees — extended dollar centrality into the commodity markets that underpin global energy trade. This arrangement, more implicit understanding than binding treaty, has shaped Gulf monetary policy for five decades and remains a live strategic question today as Saudi Arabia explores yuan-denominated oil settlement even while the riyal remains pegged to the dollar.
Financial sanctions as a tool of coercive statecraft have their own more recent lineage: the exclusion of Iranian banks from SWIFT in 2012 under EU and US pressure over Tehran’s nuclear program was the first large-scale demonstration that SWIFT access itself — not merely currency choice — could be weaponized. Russia’s disconnection from SWIFT following its 2014 annexation of Crimea was more limited, prompting Moscow to accelerate development of its domestic System for Transfer of Financial Messages (SPFS). The far more sweeping exclusion of major Russian banks from SWIFT in 2022, combined with the freezing of the Central Bank of Russia’s foreign reserves, represents the decisive inflection point examined throughout this assessment.
Strategic Context
Three structural conditions define the strategic environment in which financial statecraft now operates.
First, US fiscal deterioration has altered the political economy of dollar dominance without yet altering its market reality. Federal debt held by the public reached approximately 99 percent of GDP in fiscal year 2025, with the Congressional Budget Office projecting a rise past 100 percent in 2026 and toward 120 percent by 2036. Total outstanding Treasury securities exceed $38–40 trillion, of which foreign investors hold roughly one-third — down from approximately half a decade ago. This is a driver of reserve-diversification sentiment among reserve managers, though it has not yet translated into a broad-based flight from Treasuries, whose depth and liquidity remain without global peer.
Second, the weaponization precedent set in 2022 — the freezing of an estimated $280–300 billion in Russian central bank assets, the majority held at the Belgium-based clearing house Euroclear — fundamentally altered how sovereign reserve managers assess the risk profile of dollar- and euro-denominated assets. In December 2025, the European Union moved to indefinitely freeze these assets and advanced a proposed €140–165 billion “Reparations Loan” to Ukraine for 2026–2027, structured as an advance against the windfall interest income the frozen reserves generate rather than outright confiscation of the principal — a legally cautious approach reflecting concern over sovereign-immunity exposure, but one that nonetheless signals to non-Western central banks that reserve assets held in Western jurisdictions can be immobilized indefinitely on political grounds. This is, in the assessment of this publication, the single most important structural driver behind the gold-accumulation trend documented in the Economic Dimension below.
Third, BRICS institutional expansion has changed the bloc’s composition and its internal coherence simultaneously. Following the 2024–2025 enlargement, BRICS comprises eleven full members (Brazil, Russia, India, China, South Africa, Egypt, Ethiopia, Iran, Indonesia, the United Arab Emirates, and — with a status still treated variably across sources — Saudi Arabia) alongside ten partner states including Belarus, Kazakhstan, Malaysia, Nigeria, Thailand, and Vietnam. This diversity is simultaneously a source of collective economic weight — the bloc now represents a substantial share of global population and GDP — and a source of internal incoherence, since members’ interests in de-dollarization range from existential (Russia, under comprehensive sanctions) to strictly tactical and hedged (India, the Gulf states).
Detailed Analysis
Military Dimension
Financial infrastructure has become an explicit instrument of what scholars of geoeconomics term “financial statecraft” — the use of monetary and financial tools to achieve strategic objectives traditionally pursued through military means. The 2022 SWIFT disconnection of major Russian banks, executed in close coordination with conventional sanctions and export controls, functioned as a financial complement to Western support for Ukraine’s conventional defense, constraining Russia’s ability to finance its war economy through international capital markets even as it failed to prevent Moscow from sustaining the war through import substitution, sanctions evasion via intermediary states, and deepened financial integration with China.
The precedent is being studied closely in Beijing. Chinese financial regulators and PLA-linked strategic research institutions have, according to open-source Chinese academic and policy commentary, treated the Russia sanctions episode as a case study in “financial resilience-building” ahead of a potential Taiwan contingency, in which China would face secondary sanctions and possible SWIFT exclusion on a scale far exceeding what Russia experienced, given China’s far deeper integration into dollar-denominated global trade and finance. This connects directly to the broader question of China’s economic preparedness for a Taiwan Strait crisis — a scenario this publication has examined in depth in its companion assessment on post-Taiwan-contingency scenarios — in which financial sanctions-proofing (CIPS expansion, gold accumulation, yuan invoicing of energy imports from Russia and Iran) functions as a form of economic pre-positioning analogous to munitions stockpiling.
A secondary military-adjacent dimension involves the cyber-resilience of payment infrastructure itself. SWIFT-connected banks have historically been targeted by state-linked actors, most notably North Korea’s Lazarus Group in the 2016 Bangladesh Bank heist, and payment rails including CIPS and mBridge present an expanding attack surface as they scale. Sanctions-evasion payment channels — used, for example, in North Korea’s ammunition-for-technology exchanges with Russia, and in the “shadow fleet” oil trade sustaining both Russian and Iranian exports — represent a further military-economic dimension in which financial infrastructure and conventional logistics have become mutually reinforcing, a theme this publication has traced in its assessment of the logistics of modern war.
Political Dimension
The politics of de-dollarization are defined less by unity than by a widening gap between rhetoric and commitment among the states most associated with the agenda. President Donald Trump has repeatedly, since late 2024, threatened 100 percent tariffs against BRICS states that create or formally back a currency intended to replace the dollar, stating in one representative Truth Social post that any country attempting to do so “should say hello to Tariffs, and goodbye to America.” This threat, reiterated periodically through 2025 and into 2026, has functioned less as a response to an imminent currency launch — no BRICS common currency exists or is scheduled — and more as a deterrent signal aimed at foreclosing the option before it is seriously pursued.
The threat has, however, exposed rather than created BRICS’s internal fault line. India’s External Affairs Minister S. Jaishankar has stated publicly that India has no policy to replace the dollar and regards the dollar’s reserve-currency status as “the source of global economic stability” — a position consistent with New Delhi’s broader strategy of maintaining strategic autonomy through simultaneous engagement with Washington (via the Quad and deepening defense-technology cooperation) and with the BRICS/Global South bloc, rather than through alignment with an explicitly anti-dollar agenda. As chair of the eighteenth BRICS Summit, held in New Delhi in September 2026, India has steered the bloc’s agenda firmly toward interoperable payment infrastructure — the BRICS Cross-Border Payments Initiative and BRICS Pay — while explicitly declining to advance a common-currency roadmap.
Russia occupies the opposite pole, for reasons of necessity rather than ideological preference: with the bulk of its reserves frozen and its major banks excluded from SWIFT, Moscow has structural incentives to maximize alternative-payment adoption regardless of the economic efficiency costs involved, and Russian officials — including Deputy Foreign Minister-level statements — have consistently framed de-dollarization as a central agenda item for BRICS summitry. China occupies an intermediate position: Beijing has invested substantially in CIPS and yuan internationalization for reasons of long-term strategic autonomy and financial sovereignty, but has been notably cautious about endorsing a common BRICS currency, reflecting both technical skepticism (a shared currency would require fiscal and monetary coordination BRICS members are far from achieving) and a preference for a yuan-centered rather than a basket-currency outcome.
Economic Dimension
The empirical data through mid-2026 supports a specific and calibrated set of conclusions about the pace of dollar erosion.
Payments. SWIFT’s Global Currency Tracker for July 2026 shows the US dollar accounting for approximately 51 percent of global payment value by messaging volume, rising to roughly 60 percent when intra-eurozone payments are excluded from the denominator (a standard adjustment, since euro-area internal payments mechanically inflate the euro’s apparent share). The euro follows at approximately 22 percent, sterling at roughly 7 percent, the yen at approximately 4 percent, and the Chinese renminbi at only 2–3 percent of payment value — a figure that has drifted upward only marginally despite a decade of deliberate Chinese policy effort. In trade finance specifically — letters of credit and guarantees, which serve as a leading indicator of invoicing intentions — the dollar’s dominance is even more pronounced, at roughly 81–82 percent, with the renminbi at approximately 8 percent, reflecting China’s growing but still narrow role in financing (as opposed to settling) global trade.
Reserves. IMF Currency Composition of Official Foreign Exchange Reserves (COFER) data for the first quarter of 2026 show the dollar’s share of allocated reserves at 57.13 percent, up from 56.42 percent in the preceding quarter — a reminder that reserve-share movements are driven substantially by exchange-rate valuation effects (the dollar’s mild appreciation against major currencies accounted for roughly half of the quarter’s increase) rather than by active central-bank reallocation. The euro’s share stood at 20.03 percent and the renminbi’s at just 1.99 percent — essentially unchanged from a decade earlier despite China’s rise to the world’s second-largest economy, illustrating the gap between renminbi internationalization rhetoric and reserve-currency reality. Total global reserves stood at approximately $13.1 trillion.
Foreign-exchange turnover. The Bank for International Settlements’ April 2025 Triennial Survey recorded $9.6 trillion in average daily FX turnover, up 28 percent since 2022, with the dollar present on one side of approximately 89 percent of all transactions — a share essentially unchanged across successive surveys, underscoring the dollar’s continued function as the indispensable vehicle currency even for transactions between two non-dollar currency pairs.
Gold. The clearest and most consistent evidence of active reserve diversification lies not in currency-composition data but in physical gold accumulation. Central banks have purchased in excess of 1,000 tonnes of gold annually in most years since 2022 — roughly double the approximately 500-tonne annual average of the preceding decade — with the World Gold Council’s 2026 Central Bank Gold Reserves Survey finding a record 43–45 percent of surveyed central banks planning further gold accumulation over the following twelve months, up from just 29 percent two years prior. Gold’s valuation gains pushed it above US Treasuries as a share of official global reserves during 2025, though the World Gold Council and IMF attribute this shift primarily to price appreciation rather than a change in underlying holdings. The causal chain is explicit in central-bank commentary: reserve managers cite the 2022 Russian asset freeze directly as the event that reframed gold — physically held, domestically vaulted, and immune to third-country legal jurisdiction — as the only reserve asset genuinely free of political contingency.
Fiscal backdrop. These dynamics unfold against a US fiscal position in which debt-to-GDP is rising toward 120 percent by the mid-2030s on current CBO projections, a trend that reserve managers cite as a long-term (rather than acute) consideration in reserve diversification, consistent with what economists term Triffin-dilemma logic: the country issuing the world’s primary reserve currency must run persistent external deficits to supply that currency to the world, a structural tension between domestic fiscal discipline and international reserve-currency obligations first identified by Robert Triffin in the 1960s and increasingly cited in academic and central-bank commentary on the dollar’s long-run sustainability.
Technological Dimension
The technological competition over cross-border payment rails has bifurcated sharply since late 2024, in a development with lasting structural implications.
CIPS (China’s Cross-Border Interbank Payment System), launched in 2015, had by June 2026 grown to 210 direct participants and 1,619 indirect participants, reaching more than 5,200 banking institutions across 192 countries and regions — a scale that remains, however, an order of magnitude smaller than SWIFT’s more than 11,000 connected institutions. CIPS processed approximately ¥180 trillion in 2025 (equivalent to roughly $25 trillion at prevailing exchange rates, though estimates vary with the rate used), with a record single-day value of RMB 1.22 trillion recorded in April 2026. A structurally important caveat, frequently elided in commentary on CIPS’s growth, is that CIPS remains primarily a settlement system and continues to rely on SWIFT’s messaging layer for a substantial share of its cross-border communications — it is not yet a full messaging alternative to SWIFT, a distinction that limits the extent to which CIPS growth alone constitutes SWIFT displacement rather than complementary infrastructure.
mBridge and Project Agorá represent the clearest evidence of technological bifurcation. mBridge — a multi-CBDC wholesale settlement platform developed jointly by the Bank for International Settlements (BIS) and the central banks of China, Hong Kong, Thailand, and the UAE, joined by Saudi Arabia’s central bank as a full participant in 2024 — reached minimum-viable-product status in mid-2024. In October 2024, the BIS formally withdrew from the project, with BIS General Manager Agustín Carstens characterizing the move as reflecting the project’s technical maturity rather than a political decision; China subsequently proposed open-sourcing the platform, and the Bank of China (Hong Kong) has integrated mBridge for automated corporate payments. In the same period, the BIS launched Project Agorá, a parallel wholesale tokenization initiative involving seven G7-aligned central banks and more than forty private financial institutions, including JPMorgan, Citi, HSBC, and — notably — SWIFT itself as a private-sector participant, with testing results expected in the first half of 2026. Financial commentary has characterized this development starkly: the two projects share no overlapping central-bank membership, representing “competing answers to the same question, sponsored by competing blocs” — a bifurcation that, if it persists, would mark the effective end of the BIS’s original ambition of a single, universally interoperable multi-CBDC settlement architecture.
BRICS Pay is best understood as an interoperability layer rather than a new payment network in its own right: it aims to link existing national systems — Russia’s SPFS, China’s CIPS, India’s UPI, and Brazil’s Pix — so that transactions can route between them without requiring a dollar-denominated correspondent-banking intermediary. Reports in early 2026 also referenced a pilot “BRICS Unit,” a proposed settlement instrument reportedly backed by a combination of gold and a basket of BRICS currencies; this initiative, however, has not been confirmed through official BRICS communiqués, and Reserve Bank of India Governor Sanjay Malhotra has stated publicly that CBDC-interoperability and currency-basket proposals within BRICS remain at the discussion stage. This report treats the BRICS Unit as an unverified, low-confidence data point rather than an operational settlement currency, and flags it for reassessment as further primary-source confirmation becomes available.
Digital dollarization is the least-discussed but potentially most consequential technological counter-trend. The GENIUS Act, signed into law in July 2025, established the first comprehensive US federal regulatory framework for dollar-pegged stablecoins, requiring full 1:1 backing by cash and short-term Treasuries, monthly reserve disclosures, and annual audits for larger issuers. The stablecoin market, which reached approximately $270–300 billion in total value by mid-2026, is explicitly positioned by US policymakers — including President Trump, who described the legislation as cementing “American dominance of global finance and crypto technology” — as a vehicle for extending dollar-denominated financial access into emerging markets with weak banking infrastructure or high domestic inflation, precisely the constituencies that CBDC-based alternatives (mBridge, e-CNY) had targeted. Analysts at institutions including Brookings and the Columbia Economic Review note that this creates a structural demand channel for US Treasury securities from stablecoin reserve backing, and that “digital dollarization” — the informal adoption of dollar-pegged digital tokens by households and firms outside the United States — could deepen dollar penetration in exactly the geographies where official-sector de-dollarization is most rhetorically prominent, creating a genuine tension between state-level and household-level currency preferences that current de-dollarization commentary rarely resolves.
Legal / Diplomatic Dimension
The treatment of Russia’s frozen central bank reserves has become the central legal precedent shaping how sovereign reserve managers worldwide assess counterparty and jurisdictional risk. Approximately $280–300 billion in Russian assets were frozen by the G7, EU, and Australia beginning in February 2022, with the substantial majority — roughly €210–260 billion — held at the Belgium-based clearing house Euroclear. In December 2025, the EU agreed to indefinitely freeze (rather than release or negotiate over) these assets, and advanced a proposed €140–165 billion “Reparations Loan” to fund Ukraine’s 2026–2027 financing needs, structured to draw on the windfall interest income the frozen reserves generate — reportedly €3–5 billion annually — rather than through outright confiscation of the principal, a structure designed specifically to avoid the sovereign-immunity and expropriation-law exposure that direct seizure would entail. Belgium, as host of Euroclear, has expressed continued reservations about its own legal and financial exposure should Russia pursue litigation.
The diplomatic significance of this episode extends well beyond the Russia-Ukraine conflict itself. For non-Western central banks — including those of China, India, Saudi Arabia, and the broader Gulf — the durability of the freeze, now approaching its fifth year with no resolution mechanism beyond a Russian reparations payment that Moscow shows no intention of making, demonstrates that reserve assets held within Western jurisdictions are subject to indefinite political control under circumstances that need not involve the reserve-holding state’s own conduct in the underlying dispute. This is, in this publication’s assessment, the clearest legal-diplomatic driver of the gold-accumulation and reserve-diversification trends documented in the Economic Dimension above, and it establishes a precedent whose long-term costs to the dollar and euro systems’ credibility as neutral reserve assets may exceed its short-term utility as a Ukraine-financing mechanism — a genuine tension between the legitimate use of financial statecraft to support Ukraine and its longer-run effect on demand for Western-currency reserve assets.
A separate but related legal-diplomatic thread involves extraterritorial secondary sanctions enforced through dollar-clearing dependency: because the overwhelming majority of dollar-denominated transactions ultimately clear through US correspondent banks, Washington’s Office of Foreign Assets Control (OFAC) can impose consequences on third-country financial institutions with no direct US nexus other than their use of the dollar payment system — a jurisdictional reach that has become a central grievance driving alternative-infrastructure investment in Beijing, Moscow, and, more cautiously, in New Delhi and Gulf capitals seeking to preserve optionality rather than confrontation with Washington.
Scenario Analysis
Scenario 1 — Managed Erosion (Status Quo Persistence). The dollar’s share of reserves and payments continues its slow, uneven decline at the margins — a few percentage points per decade — driven by gradual reserve diversification into gold and, secondarily, into a broader basket of currencies, without any single alternative achieving critical mass. CIPS and mBridge continue to grow but remain regionally concentrated (predominantly Asia, the Gulf, and BRI-adjacent economies) rather than achieving global network effects comparable to SWIFT. This scenario assumes no systemic shock and continued US fiscal dysfunction that is chronic rather than acute.
Scenario 2 — Accelerated Bifurcation (Two-Bloc Financial Architecture). The mBridge/CIPS ecosystem and the Agorá/SWIFT/stablecoin ecosystem develop into genuinely parallel, low-interoperability systems, with China actively courting Belt and Road partners, Gulf states, and ASEAN economies onto its rails while the G7 bloc consolidates around tokenized dollar and euro settlement. Most Global South economies maintain dual connectivity rather than choosing exclusively, functioning as financial “swing states” whose alignment decisions carry meaningful strategic weight — a dynamic with particular relevance for South Asian and Gulf-adjacent economies, including Pakistan, navigating simultaneous relationships with China (CPEC-linked financial integration), Gulf partners, and Western-aligned institutions such as the IMF.
Scenario 3 — Crisis-Triggered Rupture. A discrete shock — most plausibly a Taiwan Strait contingency triggering China-scale secondary sanctions and a SWIFT-exclusion attempt against Chinese financial institutions, or alternatively a US debt-ceiling or confidence crisis materially impairing Treasury-market functioning — produces a rapid, non-linear acceleration of reserve diversification and alternative-system adoption, compressing into months what Scenario 1 assumes occurs over decades. This is a low-probability, high-impact tail scenario whose likelihood is nonetheless assessed as rising given the intensifying military and economic dimensions of Sino-American competition over Taiwan.
Scenario 4 — Dollar Reconsolidation via Digital Channels. Growth in dollar-pegged stablecoins under the GENIUS Act framework, combined with continued Treasury-market depth advantages, offsets or outpaces official-sector reserve diversification, such that aggregate dollar-linked financial exposure (official reserves plus private stablecoin holdings plus dollar-invoiced trade) is stable or rising even as the official-reserve dollar share continues its gradual decline — a scenario in which the headline de-dollarization narrative and the underlying financial reality diverge significantly.
Scenario 5 — BRICS Currency Breakthrough. A common BRICS reserve or settlement currency, whether commodity-backed or basket-structured, achieves meaningful adoption in bilateral and multilateral trade settlement. Given India’s explicit public opposition, the absence of the fiscal and monetary coordination mechanisms such a currency would require, and the divergent economic interests of BRICS members ranging from Iran (comprehensively sanctioned) to the UAE (a Western-aligned financial hub), this scenario is assessed as the least probable of the five outlined here within the forecast horizon.
Probability Assessment
| Proposition (by 2030 unless noted) | Probability | Key Reasoning |
|---|---|---|
| USD share of IMF COFER reserves falls below 50% | Low | Requires sustained active reallocation, not just valuation effects; no current trend supports this pace |
| CIPS annual settlement value exceeds $40 trillion equivalent | Moderate-High | Consistent with current growth trajectory (~10-20% annual growth) absent major disruption |
| A formal, circulating BRICS common currency is launched | Very Low | India’s explicit opposition; no fiscal/monetary union mechanism exists or is being built |
| mBridge and Project Agorá achieve technical interoperability with each other | Low | No overlapping central-bank membership; competing geopolitical sponsorship |
| Central banks’ gold share of reserves continues rising (by value) | High | Structural driver (reserve-asset political-risk hedging) shows no sign of reversing |
| Dollar-pegged stablecoin market exceeds $1 trillion in value | Moderate | Contingent on continued regulatory clarity and institutional adoption momentum |
| A Taiwan contingency triggers SWIFT-style exclusion attempt against China | Low (by 2030); rising thereafter | Contingent on broader cross-strait military and political trajectory, assessed separately |
| The renminbi’s SWIFT payment share exceeds 5% | Moderate | Plausible given CIPS/RMB internationalization trend, but still far below reserve-currency-scale usage |
Strategic Outlook
For policymakers, the operative planning assumption should not be “the dollar is being replaced” but “the dollar’s monopoly on financial coercion is eroding even as its monopoly on liquidity persists.” This distinction matters enormously for sanctions design: the marginal effectiveness of dollar-clearing-based sanctions against any single mid-sized economy is likely to decline over the coming decade as CIPS, mBridge-derived settlement rails, and bilateral local-currency swap lines provide functioning (if less efficient) workarounds — a dynamic already visible in the roughly two-thirds reduction in dollar usage reported in intra-BRICS trade settlement and in the near-total shift of Russia-India trade to rupee-ruble settlement. Sanctions against Russia, Iran, and North Korea have not been rendered ineffective by these workarounds, but their cost-imposition efficiency has measurably declined relative to a fully dollar-dependent counterfactual.
For financial institutions and multinational treasurers, the practical implication is the need for genuine dual-rail capability — connectivity to both the SWIFT/Agorá/dollar-stablecoin ecosystem and, where commercially relevant, CIPS and RMB-clearing capacity — rather than a binary choice, mirroring the “hedging” behavior already visible at the sovereign level among Gulf and South and Southeast Asian states.
For regional actors such as Pakistan, positioned between a deepening CPEC-linked financial relationship with China, continued dependence on IMF and dollar-denominated multilateral financing, and Gulf capital flows increasingly denominated in a mix of dollars and, tentatively, yuan, the bifurcation documented in this assessment is not an abstract great-power contest but an immediate balance-of-payments and strategic-autonomy question, requiring active management of dual financial-infrastructure exposure rather than passive alignment with either bloc.
Conclusion
The global monetary order in 2026 is best characterized not by dollar collapse, nor by de-dollarization as myth, but by structural hedging under conditions of demonstrated political risk. The 2022 freezing of Russian reserves converted an abstract, long-discussed vulnerability — that reserve assets held abroad are ultimately subject to the reserve-currency issuer’s political discretion — into a concrete, observed event, and the subsequent gold-buying surge, CIPS expansion, and mBridge/Agorá bifurcation are the rational institutional response to that demonstration. Yet the countervailing evidence is equally clear: the dollar’s share of reserves, payments, and trade finance has moved only marginally, US Treasury markets retain unmatched depth, BRICS has explicitly declined to pursue a common currency, and a new generation of dollar-pegged stablecoins may extend rather than erode dollar-denominated financial reach into the very markets alternative systems were designed to capture. The most probable trajectory through the remainder of the decade is neither dollar hegemony restored to its unchallenged 1990s form nor a genuine multipolar currency order, but a persistently bifurcated, redundant, and more expensive-to-navigate financial architecture — a world in which states and institutions increasingly maintain the capability to operate in more than one system, without fully trusting, or fully abandoning, either.
Frequently Asked Questions
Is the US dollar losing its status as the world’s reserve currency? Not currently, though it is facing gradual erosion at the margins. The dollar held approximately 57 percent of IMF-tracked official foreign exchange reserves in the first quarter of 2026, and its share has moved only slightly over the past several years, with most short-term movements attributable to exchange-rate valuation rather than active central-bank selling. No other currency holds more than roughly 20 percent of reserves.
What is CIPS and how is it different from SWIFT? CIPS (the Cross-Border Interbank Payment System) is China’s renminbi-denominated clearing and settlement infrastructure, launched in 2015. Unlike SWIFT, which is purely a messaging network that does not itself move money, CIPS combines messaging and settlement functions, but it remains far smaller in scale than SWIFT and continues to rely on SWIFT’s messaging layer for a substantial portion of its cross-border communications.
Will BRICS launch a common currency? There is no confirmed timeline or operational plan for a common BRICS currency. India, the bloc’s 2026 chair, has explicitly stated it does not support one, and the group’s official focus has shifted instead to interoperable local-currency payment infrastructure through the BRICS Cross-Border Payments Initiative and BRICS Pay.
Why are central banks buying record amounts of gold? Central-bank gold purchases have run at roughly double the pre-2022 pace, a trend that reserve managers and industry surveys attribute primarily to the demonstration effect of the 2022 freezing of Russian central bank reserves, which highlighted that foreign-held currency reserves can be rendered inaccessible through political decisions in ways that domestically vaulted gold cannot.
Could the dollar-based payment system and China’s alternative system ever fully merge or fully separate? Full separation is more likely than full merger in the near term. The Bank for International Settlements’ withdrawal from the China-linked mBridge project in 2024, and its parallel sponsorship of the G7-aligned Project Agorá with no overlapping central-bank membership, suggests the two ecosystems are developing along separate technical and governance tracks, even as most individual countries and financial institutions seek to maintain access to both rather than choosing exclusively.
Sources
- International Monetary Fund, COFER: Currency Composition of Official Foreign Exchange Reserves, data.imf.org
- IMF Data Brief, “Currency Composition of Official Foreign Exchange Reserves” (July 1, 2026), data.imf.org
- Bank for International Settlements, Project mBridge project pages and press releases, bis.org
- Bank for International Settlements, 2025 Triennial Central Bank Survey of foreign exchange turnover, bis.org
- SWIFT, Global Currency Tracker, reported via Trade Treasury Payments and Axis Intelligence Research
- World Gold Council, 2026 Central Bank Gold Reserves Survey
- Council on Foreign Relations, “How to Use Russia’s Frozen Assets” (November 2025), cfr.org
- Brookings Institution, “What is the status of Russia’s frozen sovereign assets?” and “Stablecoins after GENIUS,” brookings.edu
- CEPR VoxEU, “The dollar’s status through the lens of foreign exchange reserves” (Goldberg and Hannaoui, 2026), cepr.org
- Central Banking / Forbes, reporting on BIS withdrawal from mBridge and launch of Project Agorá
- Rio Times, “BRICS Summit 2026: 11 Members, 10 Partners Explained,” riotimesonline.com
- EBC Financial Group, “When Will BRICS Currency Be Released? What We Know in 2026,” ebc.com
- GIS Reports Online, “GENIUS Act secures dollar dominance via stablecoins” (Bob Savic, April 2026), gisreportsonline.com
- Columbia Economic Review, “Digitalizing Dominance: How the GENIUS Act Reinforces U.S. Dollar Hegemony,” cer.econ.columbia.edu
- PBS NewsHour / Associated Press, “Trump threatens 100 percent tariff on BRICS nations,” pbs.org
- China Daily, “MNCs drive expansion of China’s CIPS” (March 2026), chinadaily.com.cn
- FXC Intelligence, “CIPS volumes rise as China expands payments infrastructure” (June 2026), fxcintel.com
- Courthouse News Service, “The $300 billion hostage: Europe’s high-stakes gamble with Russia’s frozen fortune,” courthousenews.com